₹45 Lakh Home Loan EMI: Complete Repayment Breakdown
Calculate your ₹45 lakh home loan EMI and compare monthly payments, total interest, repayment amounts, eligibility and tenure options.
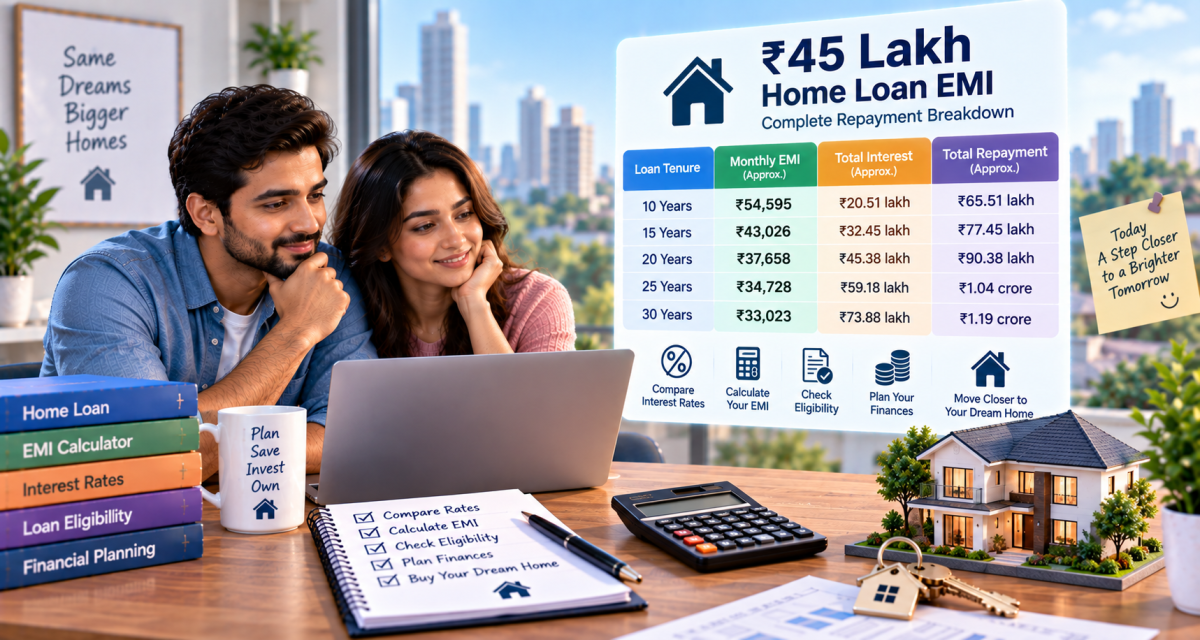
Planning to borrow ₹45 lakh for a home? Before choosing a lender, it is important to understand your 45 lakh home loan EMI, total interest, repayment amount, and eligibility. Your monthly EMI mainly depends on the loan interest rate and tenure you select.
Using an illustrative interest rate of 8% per annum, here is how the repayment can look across common home loan tenures.
₹45 Lakh Home Loan EMI at 8% Interest
| Loan Tenure | Approx. Monthly EMI | Total Interest | Total Repayment |
|---|---|---|---|
| 10 years | ₹54,595 | ₹20.51 lakh | ₹65.51 lakh |
| 15 years | ₹43,026 | ₹32.45 lakh | ₹77.45 lakh |
| 20 years | ₹37,658 | ₹45.38 lakh | ₹90.38 lakh |
| 25 years | ₹34,728 | ₹59.18 lakh | ₹1.04 crore |
| 30 years | ₹33,023 | ₹73.88 lakh | ₹1.19 crore |
Figures are approximate and calculated at an assumed 8% annual interest rate. Actual EMI and interest may vary depending on the lender's rate, loan terms, and repayment schedule.
How Is the 45 Lakh Home Loan EMI Calculated?
Lenders generally calculate home loan EMI using the standard reducing-balance formula:
EMI = P × R × (1 + R)ⁿ / [(1 + R)ⁿ − 1]
Where:
-
P = Principal loan amount, ₹45,00,000
-
R = Monthly interest rate
-
N = Number of monthly instalments
For example, at 8% interest for 20 years, the EMI is approximately ₹37,658 per month.
An emi calculator 45 lakh can help you quickly compare different interest rates and tenures before applying.
45 Lakh Home Loan EMI for Different Interest Rates
The interest rate can make a noticeable difference to your monthly repayment.
For a 20-year tenure, approximately:
| Interest Rate | Monthly EMI | Total Interest |
|---|---|---|
| 7.5% | ₹36,270 | ₹42.05 lakh |
| 8% | ₹37,658 | ₹45.38 lakh |
| 8.5% | ₹39,053 | ₹48.73 lakh |
| 9% | ₹40,486 | ₹52.17 lakh |
These figures show why comparing the 45 lakh home loan interest rate offered by different lenders can matter significantly over a long repayment period.
45 Lakh Home Loan Total Interest
The longer you keep the loan, the lower your monthly EMI generally becomes, but the total interest can increase substantially.
For example, at 8%:
-
10 years: about ₹20.51 lakh interest
-
15 years: about ₹32.45 lakh interest
-
20 years: about ₹45.38 lakh interest
-
25 years: about ₹59.18 lakh interest
-
30 years: about ₹73.88 lakh interest
This creates a trade-off between monthly affordability and overall borrowing cost. A shorter tenure can mean higher monthly payments but less interest over the full loan period.
45 Lakh Home Loan Eligibility
Your 45 lakh home loan eligibility depends on several factors rather than simply the property price.
Lenders may consider:
-
Monthly income
-
Existing EMIs and other debts
-
Credit score and repayment history
-
Age and remaining working period
-
Employment or business stability
-
Property value and location
-
Down payment available
-
Lender-specific eligibility criteria
For example, someone with a higher income and fewer existing obligations may have greater borrowing capacity than someone with the same income but several ongoing loans.
How Much Salary Is Needed for a ₹45 Lakh Home Loan?
There is no single salary figure that guarantees eligibility because lenders use their own underwriting criteria.
Your existing EMIs are particularly important. If you already have substantial monthly obligations, the amount available for a new home loan EMI may be lower.
A practical way to assess affordability is to calculate:
Net monthly income − existing EMIs − essential monthly expenses = amount available for the new EMI
You should also account for expenses such as registration, stamp duty, insurance, maintenance, and other home-buying costs rather than using your entire available cash for the down payment.
How to Reduce Your ₹45 Lakh Home Loan Interest
You can potentially reduce the overall interest burden by:
-
Choosing an affordable shorter tenure: A shorter repayment period generally reduces total interest.
-
Making part-prepayments: Additional payments toward principal can reduce the outstanding balance and future interest.
-
Increasing your down payment: Borrowing less means paying interest on a smaller principal.
-
Comparing interest rates: Even a modest rate difference can become significant over a long tenure.
-
Increasing EMI when income rises: Periodically increasing your EMI can help shorten the repayment period.
Before making a prepayment, check your lender's terms, applicable charges, and whether the reduction will be made in tenure, EMI, or both.
Should You Choose a 20-Year or 30-Year Tenure?
A 20-year loan at 8% has an estimated EMI of around ₹37,658, while a 30-year loan is around ₹33,023.
The 30-year option reduces the monthly payment by roughly ₹4,600, but the estimated total interest is much higher.
The right tenure depends on your income, existing financial commitments, emergency savings, and ability to comfortably manage the EMI. Comparing both scenarios through an emi calculator 45 lakh can make the difference easier to understand.
Final Thoughts
A ₹45 lakh home loan can have very different repayment costs depending on the interest rate and tenure. At an illustrative 8% rate, the EMI ranges from about ₹33,023 for 30 years to ₹54,595 for 10 years.
Before applying, compare the 45 lakh home loan EMI, interest rate, processing charges, eligibility requirements, and total repayment amount. Also consider whether you can comfortably manage the EMI while maintaining an emergency fund and other financial goals.
Disclaimer: EMI calculations are illustrative and do not guarantee loan approval, interest rates, or eligibility. Actual terms depend on the lender and the borrower's profile.
BankCreds helps consumers explore and compare loan options from different lenders. The platform provides loan eligibility guidance, EMI planning tools, credit insights, lender information, and educational resources to simplify financial decision-making. BankCreds does not directly provide loans; it helps users understand their options before applying. For More Details Please Visit https://bankcreds.com/

Comments (0)