Surgical Lights Market Size, Share, Industry Overview, Growth and Forecast 2026-2034
Our report has categorized the market based on type, application, and end user.
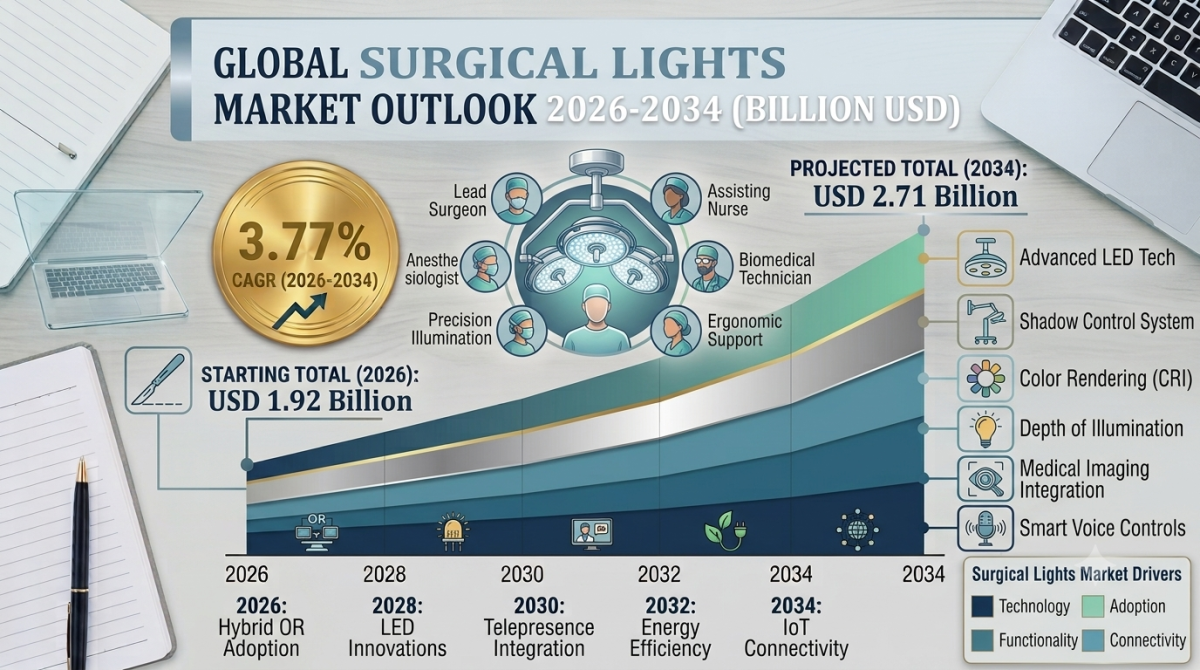
According to IMARC Group, the global surgical lights market size reached USD 1.92 Billion in 2025 and is projected to touch USD 2.71 Billion by 2034, expanding at a CAGR of 3.77% during 2026-2034. This sustained surgical lights market growth is being driven by a rising volume of surgical procedures, wider adoption of minimally invasive techniques, and the growing integration of artificial intelligence into operating room equipment.
Surgical Lights Industry Overview
Surgical lights are purpose-built illumination systems installed in operating theaters to deliver bright, shadow-free, and precisely focused light over the surgical field. A typical unit combines reflectors, lenses, a movable arm, a control panel, a power supply, and a light source that may be LED, halogen, or xenon-based. Manufacturers favor lightweight, corrosion-resistant, and easy-to-sterilize materials such as aluminum, stainless steel, medical-grade plastic, and high-clarity glass in their construction.
These systems support a wide range of surgical disciplines, including:
- Cardiac and cardiovascular surgery: High-intensity, glare-free illumination for delicate vascular and cardiac work
- Gynecological and neurosurgery: Deep-cavity lighting with adjustable focus for intricate procedures
- ENT and ophthalmic surgery: Precision beams calibrated for fine anatomical detail
- Orthopedic and cosmetic procedures: Consistent, natural-toned light that reduces surgeon eye strain
- Ambulatory and outpatient settings: Compact, mobile lighting units suited to smaller procedure rooms
Global Surgical Lights Market Size amp; Key Statistics
Below are the key statistics from IMARC Group's comprehensive analysis of the surgical lights industry:
Base Year - 2025
Historical Period - 2020-2025
Forecast Period - 2026-2034
Surgical Lights Market Size in 2025 - USD 1.92 Billion
Market Forecast in 2034 - USD 2.71 Billion
Market Growth Rate (2026-2034) - 3.77% CAGR
Largest Region - North America
Leading Type Segment - LED Lights
Leading Application - Cardiac Surgery
Leading End-Use Segment -Hospitals
Request a Sample Report for Detailed Surgical Lights Market Share Evaluation: https://www.imarcgroup.com/surgical-lights-market/requestsample
Key Market Drivers & Surgical Lights Market Trends in 2026
Several forces are shaping Surgical Lights Market Trends and reinforcing long-term growth expectations across global healthcare infrastructure:
1. Rising Volume of Surgical Procedures Worldwide
An aging global population combined with a growing burden of chronic conditions such as cancer, diabetes, respiratory disorders, and cardiovascular disease is pushing surgical caseloads steadily higher. Every additional operating room brought online, whether in a hospital or an ambulatory surgical center, represents fresh demand for high-performance lighting systems capable of supporting safe, error-free procedures.
2. Accelerating Shift Toward Minimally Invasive Surgery
Laparoscopic and endoscopic techniques increasingly require lighting systems engineered to eliminate glare and shadow while illuminating narrow, deep surgical fields. This shift toward minimally invasive approaches is a defining Surgical Lights Market Trend, prompting manufacturers to refine beam geometry and color accuracy for smaller, more precise operative windows.
3. Integration of Artificial Intelligence and Smart Controls
Next-generation surgical lights increasingly feature AI-enabled smart controls that automatically adjust beam intensity and positioning in response to the surgeon's movement, reducing shadowing and cutting down the need for manual repositioning during procedures. This intelligent automation is improving OR efficiency and is quickly becoming a differentiator among premium lighting platforms.
4. Widespread Transition to Advanced LED Technology
LED-based surgical lights are steadily displacing halogen and xenon alternatives thanks to their lower energy consumption, reduced heat output, longer operational life, and adjustable color temperature. Hospitals upgrading aging operating suites are prioritizing LED retrofits, reinforcing LED lighting's position as the leading technology segment.
5. Expansion of Ambulatory Surgical Centers
The continued growth of ambulatory surgical centers as a lower-cost, high-throughput alternative to traditional hospital operating rooms is broadening the addressable market for compact, mobile, and easy-to-install surgical lighting systems tailored to smaller procedural footprints.
6. Government Initiatives Supporting Surgical Safety
Regulatory bodies and health ministries across multiple regions are backing initiatives aimed at improving patient safety standards in operating environments, encouraging hospitals to invest in modern, compliant lighting infrastructure as part of broader surgical-suite modernization programs.
7. Healthcare Infrastructure Expansion in Emerging Economies
Rapidly developing healthcare systems across Asia-Pacific, Latin America, and the Middle East are constructing new hospitals and operating theaters at pace, creating a substantial pipeline of demand for both premium and cost-effective surgical lighting solutions in the years ahead.
Key Market Segmentation
By Type
LED Lights — Largest Segment: LED surgical lights hold the largest share of the Surgical Lights Market Share owing to their superior energy efficiency, minimal heat emission, long service life, and adjustable color rendering. Hospitals modernizing their operating suites overwhelmingly favor LED systems for both new installations and retrofit upgrades.
Halogen Lights: Halogen-based systems remain in use in cost-sensitive settings and older facilities, though their share is gradually declining as LED adoption accelerates across both developed and emerging healthcare markets.
By Application
Cardiac Surgery — Leading Application: Cardiac procedures demand exceptionally precise, glare-free illumination for delicate vascular and valve work, making this one of the highest-value application segments for premium surgical lighting systems.
Gynecological Surgery: Rising volumes of laparoscopic and reproductive-health procedures are sustaining consistent demand for adjustable, deep-cavity lighting solutions.
Neurosurgery: Neurosurgical procedures require exceptionally focused, high-clarity beams, driving demand for premium lighting systems with fine intensity control.
ENT Surgery and Others: This category spans otolaryngology, orthopedic, ophthalmic, and cosmetic procedures, each requiring tailored illumination profiles suited to their specific operative fields.
By End User
Hospitals — Largest End-Use Segment: Hospitals account for the dominant share of the Surgical Lights Market, operating the highest volume of surgical suites and driving the bulk of new equipment procurement and replacement cycles.
Ambulatory Surgical Centers: The growing preference for outpatient and same-day surgical care is expanding this segment rapidly, particularly for compact and mobile lighting formats.
Others: This includes specialty clinics, dental surgical centers, and veterinary operating facilities that require dedicated surgical illumination.
Regional Surgical Lights Market Analysis
North America — Largest
United States & Canada; advanced surgical infrastructure, high procedure volumes, early adoption of AI-enabled lighting, strong presence of leading manufacturers
Europe
Germany, France, UK, Italy, Spain; mature hospital networks, steady replacement demand, stringent operating-room safety regulations
Asia Pacific
China, Japan, India, South Korea, Australia, Indonesia; rapid hospital construction, expanding surgical capacity, rising healthcare investment
Latin America
Brazil, Mexico; expanding private hospital networks and growing surgical volumes across the region
Middle East and Africa
Healthcare modernization programs and rising investment in surgical infrastructure across the region
North America leads the global Surgical Lights Market Share, supported by a high concentration of advanced surgical facilities, early adoption of intelligent lighting technology, and the presence of several leading manufacturers headquartered in the region. Asia Pacific, meanwhile, is expected to register the fastest growth over the forecast period as healthcare infrastructure investment accelerates and surgical volumes climb across China, India, and Southeast Asia.
Connect for Detailed Surgical Lights Market Share Segmentation Analysis - Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=12617&flag=C
Leading Players in the Global Surgical Lights Industry
The global surgical lights market features a mix of established medical technology majors and specialized lighting manufacturers. Companies covered in the IMARC Group report include A-dec Inc., EPMD Group Pvt. Ltd., Getinge AB, Hill-Rom Holdings Inc. (Baxter International Inc.), Integra LifeSciences Corporation, Koninklijke Philips N.V., SIMEON Medical GmbH & Co. KG, Skytron LLC, Steris Corporation, and Stryker Corporation, among others.
Getinge AB: A long-established operating-room equipment maker known for its Maquet-branded surgical lighting platforms, including durability-focused systems designed for high-turnover operating rooms.
Stryker Corporation: A global medical technology leader offering AI-assisted surgical lighting platforms designed to integrate with its broader surgical visualization and navigation portfolio.
Steris Corporation: A major provider of ceiling-mounted and mobile surgical lighting systems with a strong global distribution and sterilization-services footprint.
Hill-Rom Holdings Inc. (Baxter International Inc.): Offers connected, IoT-enabled surgical lighting systems built for remote monitoring and predictive maintenance in modern operating suites.
Koninklijke Philips N.V.: Supplies advanced surgical lighting solutions integrated within its broader image-guided therapy and OR technology ecosystem.
Skytron LLC: A specialist manufacturer focused on ceiling-mounted and mobile surgical lighting for hospital and ambulatory surgical settings.
Integra LifeSciences Corporation: Provides surgical lighting and visualization equipment supporting neurosurgical and general surgical applications.
A-dec Inc.: Known primarily for dental and outpatient procedure lighting systems used across ambulatory and specialty clinic settings.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

Comments (0)